CTP Claims in South Australia: What Happens After a Motor Vehicle Accident
If you are injured in a motor vehicle accident in South Australia, you generally claim compensation from the Compulsory Third Party (CTP) insurer of the vehicle at fault, not from your own insurer. The scheme is fault-based: you need to show the other driver or rider was negligent, and claims are assessed under the Motor Vehicles Act 1959 (SA) and the Civil Liability Act 1936 (SA). Drivers, passengers, cyclists, motorcyclists and pedestrians can all claim if someone else caused the crash. A claim is generally expected to reach the insurer within six months, and court proceedings generally need to start within three years. Compensation depends heavily on the severity of the injury, measured against an injury scale value, and people who are catastrophically injured are covered separately, regardless of fault, by South Australia's Lifetime Support Scheme.
CTP claims in South Australia at a glance: Fault-based scheme | Claim goes to the at-fault driver's CTP insurer | Lodge within around 6 months | Court proceedings within 3 years
Most people have never had to think about how CTP insurance works until the day they need it. By then there is a police report to sort out, an insurer asking for a claim form, medical appointments to attend, and often lost income to manage, all at once and usually while still recovering from the crash itself.
This guide sets out how the South Australian CTP scheme works, who can claim, what happens after a crash, how compensation is worked out, and where the time limits sit. It also covers what happens when the at-fault vehicle cannot be identified or was uninsured, when a workplace accident changes things, and why the timing of a settlement offer deserves more caution than most people expect.
Key takeaways
A CTP claim in South Australia is not automatic and it is not the same process as claiming on your own car insurance policy. The points below cover the parts that most often catch people out.
- The claim is made against the CTP insurer of the at-fault vehicle, under a fault-based scheme regulated by the CTP Insurance Regulator.
- Drivers, passengers, cyclists, motorcyclists and pedestrians can all claim if another person's negligence caused the injury.
- A claim should generally be lodged within around six months of the accident, and reported to police promptly where anyone was injured.
- Court proceedings generally must be commenced within three years of the accident under the Limitation of Actions Act 1936 (SA).
- What you can recover, including pain and suffering, depends on an injury scale value assessed once your condition has stabilised.
- Catastrophic injuries are covered separately by the no-fault Lifetime Support Scheme, whatever the outcome of the fault-based CTP claim.
Summary table
The table below is a quick reference only. According to the CTP Insurance Regulator and the Limitation of Actions Act 1936 (SA), the practical position for most South Australian CTP claims is as follows.
| Issue | Practical position | Source |
|---|---|---|
| Who pays | The CTP insurer of the at-fault vehicle | CTP Insurance Regulator |
| Legal basis | Fault-based, negligence must be shown | Motor Vehicles Act 1959 (SA); Civil Liability Act 1936 (SA) |
| Claim lodged with insurer | Generally within about 6 months of the accident | SA Law Handbook, Legal Services Commission of SA |
| Court proceedings | Generally within 3 years of the accident | Limitation of Actions Act 1936 (SA) s 36 |
| Vehicle unidentified or uninsured | Claim proceeds against the Nominal Defendant | Motor Vehicles Act 1959 (SA), Part 4 |
| Catastrophic injury | Covered regardless of fault by the Lifetime Support Scheme | Motor Vehicle Accidents (Lifetime Support Scheme) Act 2013 (SA) |
How South Australia's CTP scheme works
Every vehicle registered in South Australia carries CTP insurance, and the premium is paid as part of registration. That insurance does not cover damage to your own vehicle. It exists to cover claims for personal injury or death caused to other people by the use of that vehicle when its driver is at fault, whether the crash was a minor bingle or a serious collision.
Five government-approved insurers currently provide CTP cover in South Australia: AAMI, Allianz, NRMA, QBE and Youi. Whichever insurer covers the vehicle that caused the crash is the insurer you claim against, not your own CTP insurer or your own car insurer. The CTP Insurance Regulator, an independent statutory authority established under the Compulsory Third Party Insurance Regulation Act 2016 (SA), oversees those five insurers, sets the premium framework and monitors how claims are handled.
South Australia's scheme remains fault-based. Unlike some no-fault statutory benefit models used interstate, a South Australian claimant generally needs to establish that another driver or rider was negligent before a common law claim for damages proceeds, and the claim is then assessed under the Civil Liability Act 1936 (SA). Where a person was entirely responsible for their own accident, for example a single-vehicle crash with no other party at fault, there is usually no CTP claim available for their own injuries, since there is no negligent third party to claim against.
The Nominal Defendant: when the vehicle is unidentified or uninsured
Not every crash involves a clearly identified, insured vehicle. Hit-run drivers and unregistered vehicles still cause injuries, and the scheme accounts for that. Where the at-fault vehicle cannot be identified, or turns out to be uninsured, the Regulator is appointed as the Nominal Defendant under Part 4 of the Motor Vehicles Act 1959 (SA) and effectively stands in the insurer's place. The Regulator then assigns day-to-day management of that claim to one of the five CTP insurers.
Practically, that means a hit-run victim is not left without a claim simply because the other driver disappeared. It does mean the evidence has to work harder. A court needs to be satisfied that reasonable steps were taken to identify the vehicle, which is one of several reasons a police report and a prompt statement matter even when it feels like nothing will come of them.
Who can make a CTP claim
The CTP Insurance Regulator treats road users broadly. Drivers, passengers, motorcyclists, cyclists and pedestrians can each bring a claim, provided the injury resulted from someone else's negligent use of a motor vehicle.
- A driver or rider who was not entirely at fault for the accident.
- A passenger injured in a crash, including where the vehicle they were travelling in was the only one involved and its driver was at fault.
- A pedestrian struck by a vehicle.
- A cyclist or other rider of a device struck by, or in a collision involving, a motor vehicle.
- A motorcyclist injured by another driver's negligence.
Age is not a bar to claiming. A child injured as a passenger can have a claim made on their behalf, generally through a litigation guardian, and different practical time limits can apply while a claimant is a minor. Establishing whose negligence caused the crash still matters in every category, even where liability looks obvious.
Those affected by a road crash, whether as a driver, cyclist or pedestrian, can discuss their position through the firm's motor vehicle accident compensation service.
Making a claim: what happens after the crash
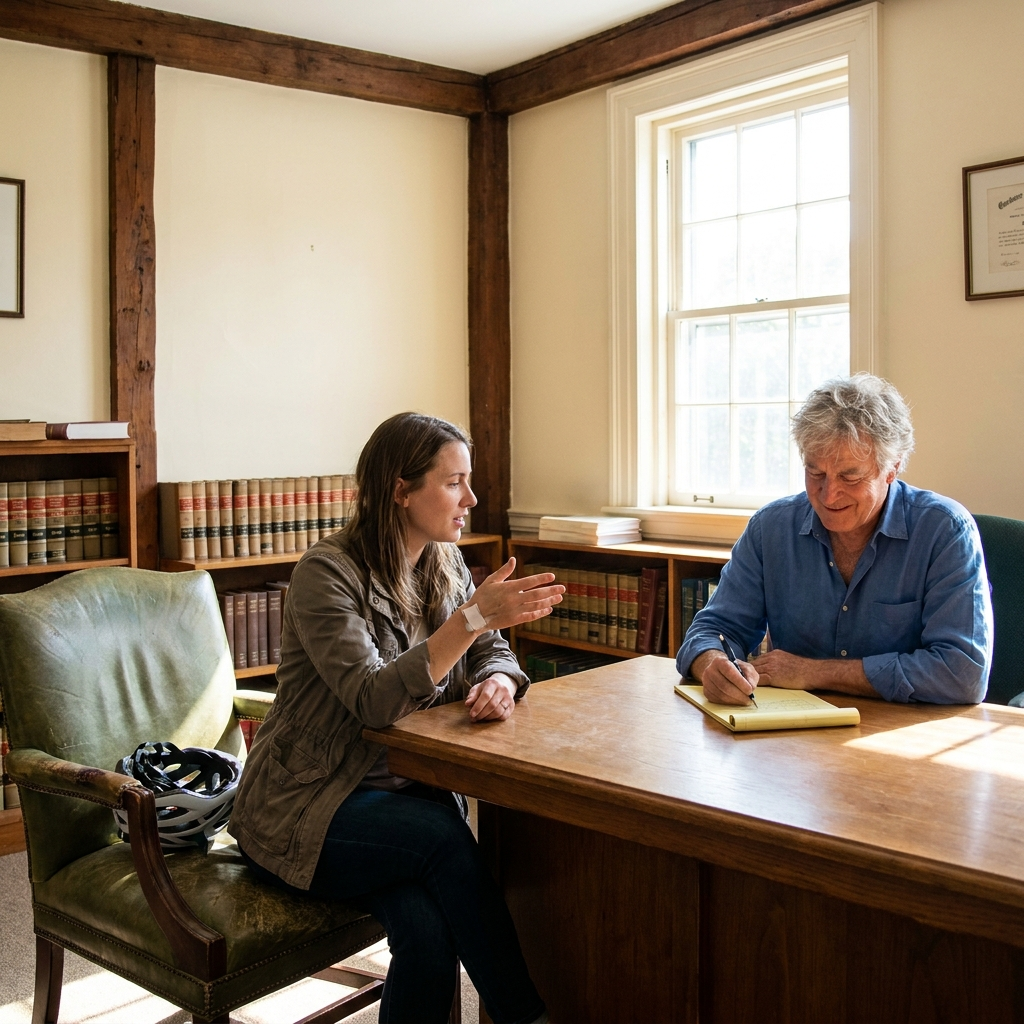
What you do in the days after a crash affects the claim later, sometimes more than people expect while they are still dealing with the immediate aftermath.
Immediate steps and evidence
Drivers involved in a crash causing injury or death must stop, give assistance, and present to police within 90 minutes under the Road Traffic Act 1961 (SA) section 43. Separately, under the Australian Road Rules as they apply in South Australia, an accident generally needs to be reported to police within 24 hours where someone was injured or killed, where details were not exchanged, where a vehicle needed to be towed, or where property damage looks like it will reach 3,000 dollars or more.
Beyond the legal obligation, a police report gives the claim a reference point: the report number is needed to complete the CTP claim form, and it becomes part of the evidence the insurer relies on to assess fault. Where the identity of the other vehicle is uncertain, reporting to police as soon as possible, rather than waiting to see how symptoms develop, protects a later claim against that vehicle or against the Nominal Defendant.
Photographs of the vehicles, the road, and any visible injuries, contact details for witnesses, and a written note of what happened while it is still fresh all help later. Medical records matter just as much: attending a doctor promptly, following the treatment that is recommended, and keeping certificates, invoices and reports creates a contemporaneous account of the injury rather than a reconstructed one months later.
Lodging the claim
The claim itself is made on the standard Injury Claim Form, sent to the at-fault vehicle's CTP insurer. The form asks for the circumstances of the accident, the police report number, and details of the injury and treatment so far. Where the identity of the other vehicle is unknown or it was uninsured, the claim must be lodged as soon as reasonably practicable after that is discovered. Drivers have a separate duty: under section 124 of the Motor Vehicles Act 1959 (SA), a driver involved in a crash where someone was injured or killed must give the vehicle's CTP insurer written notice of the accident, and failing to do so is an offence carrying a penalty of up to 1,250 dollars or imprisonment of up to three months.
Once the insurer receives the completed form, it allocates a claim number and explains the next steps. That does not mean the claim is accepted. Insurers investigate liability, may request further medical information, and can dispute the extent of the injury well before any offer is made.
What compensation can cover, and the thresholds that decide it
Compensation under a CTP claim is not a single lump sum calculated the same way for everyone. It is built from several heads of damage, each with its own legal test, and the value of most of them depends on an injury scale value (ISV) assessed once the injury has stabilised.
Pain and suffering and the injury scale value
Under the Civil Liability Act 1936 (SA), a person injured in a motor vehicle accident can only be awarded damages for non-economic loss, commonly called pain and suffering, if the injury scale value exceeds 10. Below that point, the injury is treated as not serious enough for a pain and suffering award, regardless of how the person experienced it. A court retains a narrow discretion to award damages below that threshold where the consequences of the injury are exceptional compared with other cases of the same kind and applying the threshold would be harsh and unjust, but that exception is applied cautiously rather than routinely.
Economic loss, medical costs and care
Lost income is treated differently to pain and suffering. The Act excludes the first week of lost earning capacity from a claim, caps the total award for loss of earning capacity, and applies a further statutory discount of 20 percent to damages for lost or impaired earning capacity arising from a motor vehicle accident.
Reasonable and necessary treatment expenses, such as medical, hospital, physiotherapy and pharmaceutical costs connected to the injury, are generally recoverable in full where properly supported by evidence. Care provided by a family member, commonly called gratuitous or voluntary care, can also be compensated, but only once the injury scale value exceeds 10 and the care has been provided for at least six hours a week over at least six months, and the total recoverable for that care is capped by reference to state average weekly earnings rather than the market cost of paid care.
None of these figures are things a claimant should try to estimate alone. The insurer's own assessment of the injury scale value will usually be conservative, and it directly determines which heads of damage are even available.
Catastrophic injuries and the Lifetime Support Scheme
Some injuries fall outside the fault-based scheme altogether. Since 1 July 2014, people who sustain a catastrophic injury in a motor vehicle accident on a South Australian road, such as a spinal cord injury, serious traumatic brain injury, amputation, severe burns or permanent blindness, can access treatment, care and support through the Lifetime Support Scheme under the Motor Vehicle Accidents (Lifetime Support Scheme) Act 2013 (SA), administered by the Lifetime Support Authority. This applies regardless of who caused the accident, including cases with no identifiable at-fault driver.
The Lifetime Support Scheme does not replace a CTP claim. It funds treatment, care and support, not pain and suffering or economic loss, so a person catastrophically injured in a crash caused by someone else's negligence generally still needs a separate CTP claim to recover those losses, with the Lifetime Support Scheme sitting alongside it for lifetime care needs.
Time limits, settlement offers and the workers compensation overlap
The time limit to start court proceedings
Under section 36 of the Limitation of Actions Act 1936 (SA), an action for damages that includes personal injury must generally be commenced within three years of the date the cause of action arose, which for a motor vehicle accident is usually the date of the crash. Where an injury is latent and only becomes apparent later, the three years generally runs from when the injury first came to the person's knowledge rather than the date of the accident itself. Missing the deadline does not automatically end a claim, but seeking an extension of time is a court application in its own right, with no guarantee of success, so it should never be relied on as a backup plan.
Before you accept a settlement offer
Insurers are not required to make their best offer first, and a CTP file is often at its least favourable to the injured person before medical evidence, future care needs and lost earning capacity have been properly worked out. Once a settlement is accepted and a deed of release signed, the claim is generally finished, even if symptoms later prove worse than expected or a related cost emerges that nobody anticipated. Getting advice before signing anything, not after, is the point at which it actually helps, and the firm's motor vehicle accident compensation lawyers can review an offer against the medical evidence before you decide.
If the crash happened at work
If a motor vehicle accident happened while you were working, for example a delivery driver, a tradesperson travelling between jobs, or a commute that falls within work duties, a workers compensation claim through ReturnToWorkSA may also be available on a no-fault basis. Running both a workers compensation claim and a CTP claim is possible, but ReturnToWorkSA can seek to recover what it has paid out from a later CTP settlement, so the two claims interact rather than simply adding together. This is worth raising early with whoever is advising you, rather than assuming the two payments are separate and unconnected.
Why legal advice matters when making a CTP claim
You do not need a lawyer to lodge or manage a CTP claim, and plenty of straightforward claims are resolved without one. Advice becomes more valuable once the injury scale value is contested, once future economic loss or care needs are in dispute, once a settlement offer is on the table, or once liability itself is unclear, because those are the points where an insurer's assessment and a fair outcome can differ most sharply.
A lawyer acting on a CTP claim typically reviews the police report and medical evidence for gaps, checks that the injury scale value reflects the medical picture rather than an early or incomplete assessment, calculates economic loss with the statutory discounts and thresholds applied correctly, and tests a settlement offer against what the claim is actually likely to be worth before advising whether to accept it. Steven Clark is actively involved in supervising operations and overseeing standards of work. That matters on files where a single incorrect threshold calculation can change the outcome by a substantial margin.
Anyone dealing with a CTP claim, or a broader personal injury following a motor vehicle accident, can discuss their situation through the firm's personal injury lawyers page, or contact the office directly through the contact page.
Speed is the enemy of a fair CTP settlement
My view is that the biggest risk in a CTP claim is not the paperwork, it is timing. An early settlement offer arrives while a client is still recovering, still hoping the injury will resolve faster than it will, and often keen to have the whole process behind them. That is exactly when an offer looks more attractive than it should.
We do not act on a no win no fee basis, and I think that matters more in CTP work than in most other areas. A no win no fee arrangement can create pressure to settle a file quickly once costs are being carried against an uncertain outcome, which puts the practice's interests too close to a decision that should be made purely on what is right for the client. Our view is that the client carries that decision, informed by proper medical evidence and a clear costs arrangement agreed at the outset, not by pressure on either side to close the file.
The other pattern I see is people accepting an early figure because the immediate expenses, lost wages and medical bills are pressing, without knowing whether their injury has actually finished causing them problems. An injury scale value assessed too early can understate a genuine injury, and once the deed of release is signed, that assessment is generally the end of the matter. Patience, proper medical evidence and a realistic view of the injury scale value protect a client far more reliably than accepting the first figure an insurer puts forward.
This article is general information about the South Australian CTP scheme, not legal advice about any particular claim.
References
CTP procedures, thresholds and forms can change, and individual circumstances affect how the scheme applies to a particular claim. Readers should confirm current requirements with the CTP Insurance Regulator or their own legal adviser rather than relying on this article alone.
- Compulsory Third Party (CTP) Insurance Scheme, SA Law Handbook, Legal Services Commission of SA
- Catastrophic Injuries and the Lifetime Support Scheme, SA Law Handbook, Legal Services Commission of SA
- Legal obligations after a motor vehicle accident, SA Law Handbook, Legal Services Commission of SA
- CTP Insurance Regulator, who can claim
- Motor Vehicles Act 1959 (SA), South Australian Legislation
- Civil Liability Act 1936 (SA), South Australian Legislation
- Limitation of Actions Act 1936 (SA), South Australian Legislation
- Motor Vehicle Accidents (Lifetime Support Scheme) Act 2013 (SA), South Australian Legislation
Frequently asked
Questions about this
Who pays a CTP claim in South Australia?
The Compulsory Third Party insurer of the at-fault vehicle pays the claim, not your own insurer. South Australia's CTP scheme is fault-based, so you generally need to show the other driver or rider was negligent before compensation is payable.
How long do I have to make a CTP claim in South Australia?
A claim is generally expected to be lodged with the at-fault vehicle's CTP insurer within six months of the accident, and court proceedings must generally start within three years under the Limitation of Actions Act 1936 (SA). Waiting reduces your options, so early advice matters.
Can a cyclist or pedestrian make a CTP claim?
Yes. The CTP scheme covers drivers, passengers, motorcyclists, cyclists and pedestrians injured by a motor vehicle, provided the injury was caused by someone else's fault. A driver who was entirely at fault cannot claim against their own conduct.
What happens if the vehicle that hit me cannot be identified or was uninsured?
The CTP Insurance Regulator is appointed as the Nominal Defendant under the Motor Vehicles Act 1959 (SA) and stands in for the missing or uninsured insurer. You still need to report the accident to police and take reasonable steps to identify the vehicle.
Do I need a lawyer to make a CTP claim in South Australia?
No, you can lodge and manage a claim yourself. Legal advice becomes more important once an insurer makes a settlement offer, or where the injury scale value, future economic loss or care needs are in dispute, because those figures are usually contested.
What if the car accident happened while I was at work?
You may be able to pursue a workers compensation claim through ReturnToWorkSA as well as a CTP claim, but ReturnToWorkSA can seek to recover its outlay from a CTP settlement. Get advice before running both claims so the interaction does not reduce your overall position.